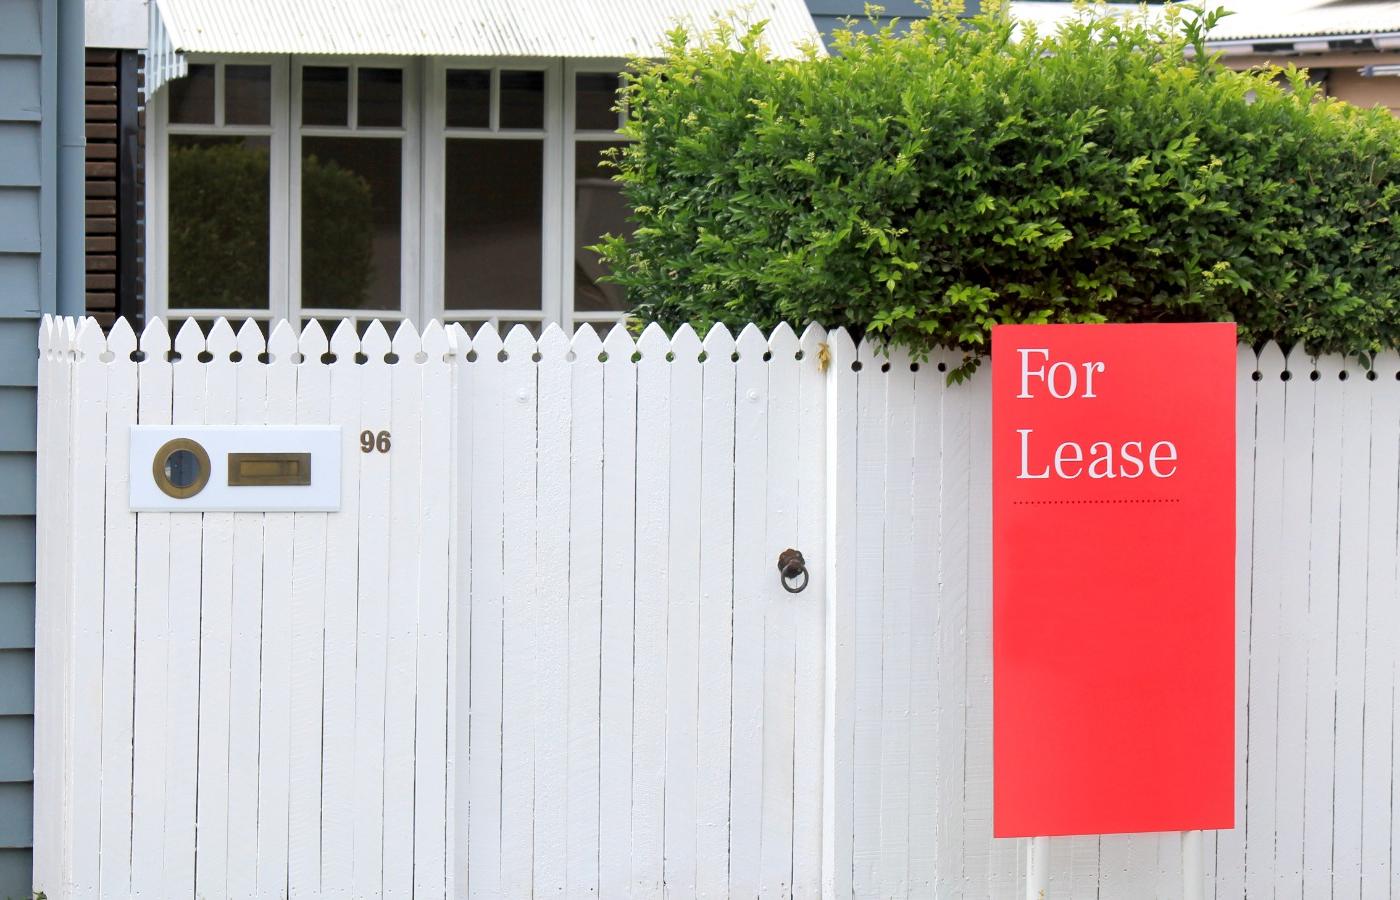
The Reserve Bank’s warning that a deeper housing slowdown could become a risk to the Australian economy carries growing implications for the real estate industry, with the first weeks of spring already showing the effects of tighter borrowing capacity, softer buyer competition and greater pressure on vendor expectations.
Australia’s real estate industry is three weeks into the spring selling season with the Reserve Bank weighing another potential interest rate increase against mounting evidence that housing activity is already slowing.
RBA Governor Michele Bullock told the House of Representatives Standing Committee on Economics that housing conditions had softened and that a larger than expected easing could become a downside risk to economic activity.
Housing prices remain around 50 per cent above early 2020 levels, but conditions beneath that headline figure have shifted considerably.
Prices have fallen across most capital cities, housing finance has weakened, auction activity is running well below last year and buyers are increasingly constrained by the amount lenders are prepared to advance.
For real estate businesses, the consequences extend well beyond movements in national dwelling values.
Transaction volumes, days on market, clearance rates, listing conversions, vendor expectations, investor participation and ultimately agency revenue are all being reshaped by a market in which finance has become one of the strongest constraints on purchasing decisions.
Transaction volume is becoming the bigger issue
For residential agencies, falling property prices are not necessarily the greatest commercial risk.
Falling turnover is.
Agencies can continue to perform in a declining price environment provided buyers and sellers continue to transact.
The greater challenge emerges when vendors remain anchored to previous market conditions while buyers are operating with lower borrowing limits.
That gap is beginning to show.
Properties are taking longer to sell, vendor discounting has increased and advertised stock has risen compared with a year earlier.
For agents, the result is a very different listing environment from the one that prevailed during periods of rapid price growth.
Winning a listing remains important, but correctly positioning the property from the beginning is becoming increasingly critical.
Campaigns launched above the level finance-approved buyers are prepared or able to pay risk remaining on the market longer, requiring later price adjustments and becoming progressively harder to re-energise.
The best-performing agents through this period will increasingly be those able to demonstrate the market to vendors early and convert changing conditions into realistic pricing decisions.
Buyer enquiry is no longer the same as buyer capacity
One of the defining features of the current spring market is the growing separation between buyer interest and buyer purchasing power.
Rate increases affect both.
Higher repayments can make purchasers more cautious, but tighter serviceability assessments can also reduce what a buyer is physically able to borrow.
New housing loan commitments fell 5.4 per cent in the June quarter, including declines among both owner-occupiers and investors.
That creates a more complicated market for sales teams.
Open homes may remain busy.
Online enquiry can remain strong.
A property can attract multiple interested parties.
But fewer of those buyers may have the financial capacity to transact at the vendor’s preferred price.
Buyer qualification therefore becomes increasingly valuable.
Understanding pre-approval status, available deposit, finance conditions and realistic purchasing limits earlier in the relationship can prevent agents spending weeks negotiating with demand that cannot convert.
It also increases the importance of relationships between agencies, mortgage brokers and finance professionals as buyers reassess what they can afford.
Spring auctions are exposing the change in conditions
The first weeks of spring are already showing how significantly auction conditions have changed.
Capital city auction volumes remain materially below the same period last year, despite the seasonal increase in listings normally associated with September.
Clearance rates have also remained well below the strongest levels recorded during more competitive phases of the market.
In some areas, a greater number of properties are passing in as the gap between vendor expectations and buyer capacity becomes harder to bridge.
That places more responsibility on agents before auction day.
Price feedback, bidder qualification, reserve discussions and vendor management need to begin well before the final stages of the campaign.
Where competition is thinner, the quality of the agent becomes considerably more visible.
An experienced auction agent can still create competitive tension and secure a strong result in softer conditions.
But strategies developed in a market with five or six confident bidders cannot simply be transferred into one where two serious buyers arrive with firm lending ceilings.
More affordable property is gaining importance
The housing adjustment is not uniform.
Higher-value markets have experienced some of the largest falls, particularly in Sydney and Melbourne, while more affordable houses, townhouses and units have generally shown greater resilience.
That creates an important opportunity for agencies.
Buyers do not necessarily disappear when borrowing capacity falls.
They adjust.
A buyer previously targeting a detached house may shift to a townhouse.
A townhouse buyer may move towards an apartment.
Others may expand their search into surrounding suburbs or regional markets where their borrowing capacity stretches further.
Investors may also reassess locations and dwelling types where rental yield and servicing remain more attractive.
Agencies with stock across multiple price points can capture that movement rather than treating reduced borrowing power solely as lost demand.
For principals, understanding where buyers are moving may now be as important as understanding where median prices are moving.
Investor weakness creates different effects across agency businesses
The decline in investor finance presents both risks and opportunities for the industry.
For sales businesses with a strong investor client base, reduced participation can weaken competition for apartments, entry-level houses and other stock traditionally purchased for rental.
It can also reduce repeat transaction activity from portfolio investors.
Property management businesses face a different equation.
If higher interest rates keep prospective first-home buyers renting for longer, tenant demand can remain elevated.
At the same time, if fewer investors purchase rental properties, the underlying shortage of rental accommodation may become more difficult.
Australia’s broader housing undersupply has not disappeared because prices have softened.
For rent-roll businesses, that increases the importance of landlord retention, service quality and demonstrating the value of professional property management.
In an environment where winning new investor clients becomes more competitive, protecting the existing rent roll becomes even more valuable.
Softer prices can bring buyers back
The housing slowdown is not entirely negative for the industry.
Australia entered the current correction after an exceptional increase in residential property values.
Housing prices remain around 50 per cent above their early 2020 levels, and affordability remains stretched in many markets.
A period of more moderate pricing can allow some buyers to return.
This is particularly relevant to first-home buyers and owner-occupiers who have spent recent years watching values rise faster than their deposits or borrowing capacity.
Lower prices do not automatically restore affordability while interest rates remain elevated.
But a market with greater stock choice, longer selling periods and more negotiable vendors can create transactions that were previously impossible.
For agents, dormant buyer databases may therefore become increasingly valuable.
Buyers who stopped attending open homes because they believed they could not compete may reconsider as stock levels rise and negotiating conditions improve.
The opportunity is not simply to find new buyers.
It is to identify which previously inactive buyers can now transact.
Vendor management will define performance
The current market will increasingly expose the difference between obtaining listings and successfully managing them.
In a rapidly rising market, momentum can disguise poor pricing.
In a softer market, it cannot.
Agents need to explain why a comparable sale from three or six months earlier may no longer reflect the amount today's buyers can finance.
They also need to distinguish between enquiry and executable offers.
The businesses that address those conversations early can continue to transact.
Those that secure listings by reinforcing unrealistic expectations risk building stock while conversion rates deteriorate.
Changing market conditions can also create opportunities for experienced agents to gain share.
Strong communication, accurate pricing, disciplined negotiation and the ability to retain vendor confidence through a longer campaign become more valuable as conditions become less forgiving.
Principals need to watch the numbers inside their own businesses
For agency owners, the implications of another possible RBA increase are best measured through operating performance rather than national headlines.
The critical questions are increasingly straightforward.
How many listings are being taken?
How many are selling?
How long are campaigns running?
How many qualified buyers sit behind each listing?
How large is the gap between vendor expectations and written offers?
How many contracts are failing because of finance?
How is gross commission income per transaction changing?
What proportion of the rent roll is exposed to investor sales?
Those figures will reveal more about the impact of higher rates on an individual agency than a national median price result.
A business with strong listing conversion, disciplined vendor management, effective buyer qualification and a well-retained rent roll can continue to perform in a declining price environment.
A business dependent on rapidly rising prices to generate urgency will find the adjustment considerably more difficult.
Another hike would deepen an adjustment already underway
The Monetary Policy Board meets on 28 and 29 September with inflation still above its target range and financial markets increasingly expecting another increase in the cash rate.
Housing prices themselves will not determine that decision.
But the property industry is already providing evidence that tighter monetary policy is flowing through the economy.
Prices have softened.
Finance activity has weakened.
Investor participation has fallen.
Auction volumes remain below last year.
Properties are taking longer to sell.
Vendor discounting has increased.
Buyers have more choice.
Another rate increase would intensify those pressures at a point when the spring market is already revealing how much conditions have changed.
There are also opportunities within that adjustment.
More realistic pricing can restore transaction flow.
Softer values can bring previously excluded buyers back into the market.
Demand can shift towards more affordable stock rather than disappear altogether.
Property management remains supported by structural undersupply.
Experienced agents can gain market share as vendors place greater value on accurate advice and strong negotiation.
The real estate industry does not require continuously rising property prices to perform.
It requires buyers and sellers to meet.
For the remainder of spring, the industry's challenge will be whether agents can narrow the gap between vendor expectations and buyer purchasing power quickly enough to keep transactions moving.
 The Morning BriefWith Jake and MiaListen now
Tell us what’s happening
Trending
ESTABLISHED FAMILY AGENCY JOINS FIRST NATIONAL IN TOWNSVILLE
Network News
Meta puts organic links and human support behind $76.99 business tier
Technology & PropTech
Growth Is Getting Smarter: What Real Estate Leaders Are Looking For Now
Opinion
Harcourts Establishes New Presence in Canberra with Gungahlin | Belconnen Launch
Network News
REA must give agencies a 25% downgrade option from January
Industry News
This article was independently written and edited by Real Estate Today. © Real Estate Today 2026 – All Rights Reserved.
Real Estate Today is an independent real estate industry publication covering Australia and New Zealand.